Weekly Economic Review

Weekly Economic Review

17 November 2026

Global and Thai Economy


Inflation supports year-end rate hikes in US and Japan. Thailand’s growth outlook improves over economic momentum and statistical revision.


Global


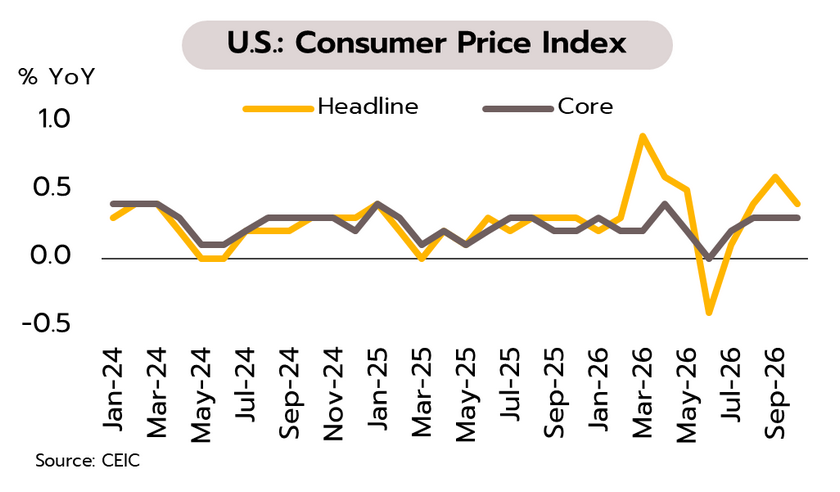
U.S.: Elevated inflation risks support a December rate hike, but the need for further tightening is diminishing. Headline inflation rose by 0.4% MoM in October, above market expectations of 0.3% but slowing from 0.6% in September, while core inflation held steady at 0.3% MoM. Producer price inflation edged up from 6.3% to 6.5% YoY, its highest rate in nearly four years. Inflationary pressures support the likelihood of another 25-bp Fed rate hike in December to 4.00–4.25%. However, easing headline inflation, declining oil prices, and slower wage growth (4.13% YoY in September vs. 4.22% in August) should help contain second-round inflation risks, reducing the need for additional tightening thereafter.

Weekly Economic Review

Japan: Inflationary pressures drive the sharpest contraction in household spending in six years, but the BOJ is likely to continue raising rates. Household spending fell 6.8% YoY in September, the steepest decline in six years and the tenth consecutive monthly contraction. Spending declined across almost all goods and service categories, reflecting pressure from rising living costs. Meanwhile, Tokyo headline inflation accelerated to 2.8% YoY in October. Persistent inflationary pressures, coupled with continued wage growth, point to clearer signs of second-round effects. The BOJ is therefore likely to raise its policy rate by 25 bps to 1.50% in December and may signal one or two additional hikes in 2027.


Thailand


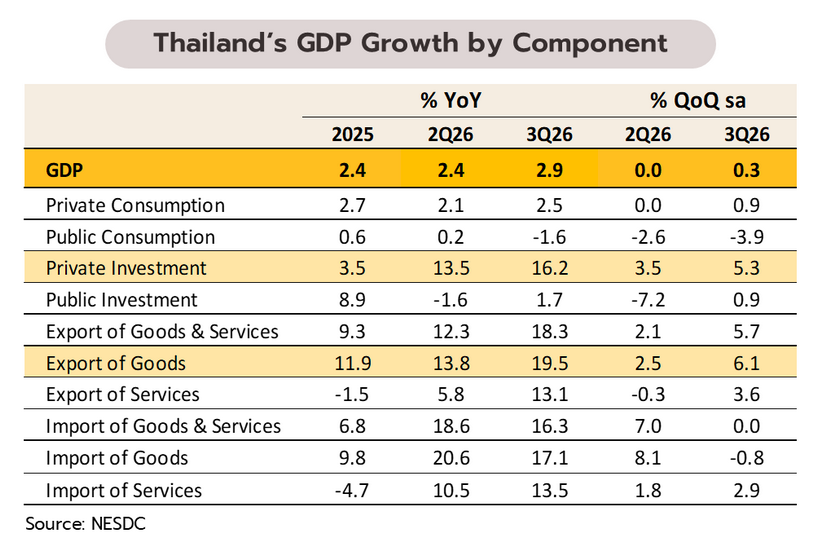
Thailand’s 3Q26 GDP growth accelerated to 2.9% from 2.4% in 2Q26, underpinned by stronger investment momentum, robust export growth, and stimulus measures. Global demand for AI and electronics boosted private investment and exports while moderating imports contributed to the current account’s return to surplus in 3Q26. Meanwhile, a sharp inventory drawdown weighed on GDP growth. For full-year 2026, the NESDC projects GDP growth of 2.5%, reflecting stronger investment and export expansion. For 2027, the NESDC projects GDP growth in a range of 2.0–3.0%.

Weekly Economic Review

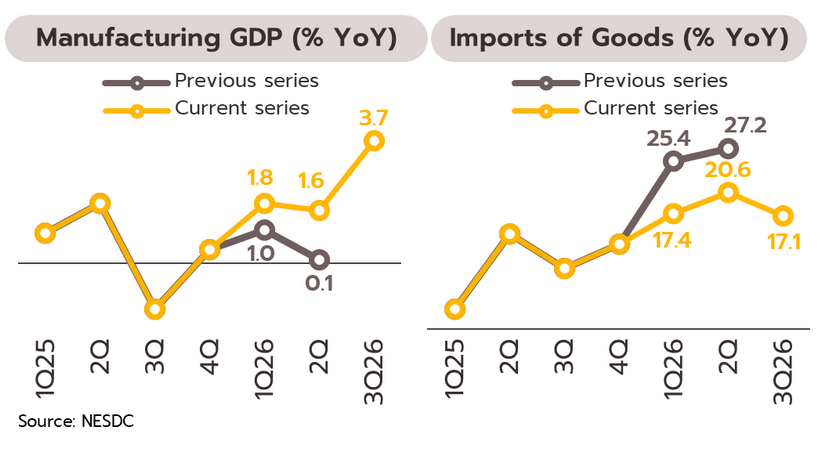
Recent developments suggest that we are likely to revise up our GDP growth forecast of 2.1% (as of August 26), due to the following factors. First, stronger-than-expected 3Q26 GDP growth suggests that underlying economic momentum has strengthened. Second, recent statistical revisions point to stronger reported growth. The revised Manufacturing Production Index (MPI) could lead to the acceleration in manufacturing GDP growth to +3.7% YoY in 3Q26 and upward revisions to growth in earlier quarters (see chart). Lowered measured goods imports (see chart) by excluding contract-manufacturing transactions could raise reported GDP growth. Third, government policies, including Thai Chuay Thai Plus program, flood-relief assistance, should provide additional support. Nonetheless, downside risks remain significant, such as geopolitical tensions and U.S. policy uncertainty. We are reassessing our baseline and plan to release updated GDP forecasts by early December.
 
Weekly Economic Review

 
Announced :17 November 2026
Back
Press keyword to search